The Bceao sets the rules of the game October 5, 2026
As of September 30, the WAEMU Instant Payment System Interoperable Platform (Pi-Spi) had 175 connected structures. Thus, from November 2, 2026, interoperable electronic money transactions within UEMOA must be carried out through this infrastructure, with a significant free policy.
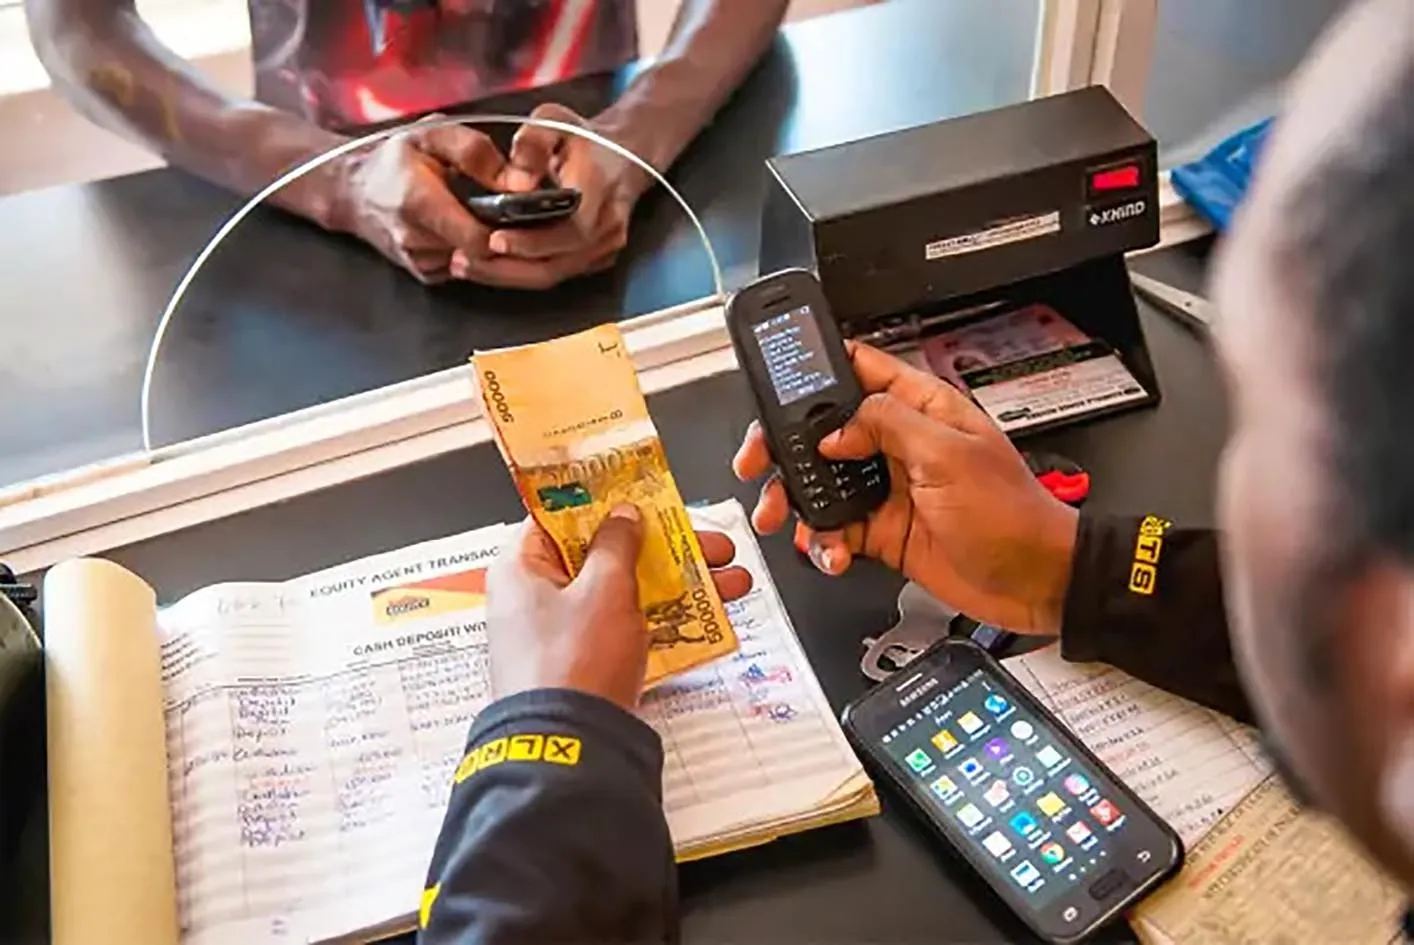
The WAEMU Instant Payment System (Pi-Spi) Interoperable Platform, launched on September 30, 2025, currently has 175 participants connected and allows more than 38 million people to access instant payment services. In Senegal, 43 structures are connected, the largest ratio per country. In a press release dated October 2, 2026, the Central Bank of West African States (Bceao) defines the operating methods of the system. It underlines that from November 2, 2026, interoperable electronic money transactions within UEMOA must be carried out through the Pi-Spi interoperable Platform. When sent, national transfers whose daily cumulative amount is less than or equal to 8,000 FCfa per user and per participant, are free, without limitation on the number of operations. At this threshold, indicates the Bceao, free coverage covers 75% of electronic money transactions in the UEMOA. National transfers for an amount greater than 8,000 FCfa may be subject to fees whose rate is between 0 and 0.8%. It is applied to the amount excluding taxes of the transfer. At reception, transfers are free, with no limit on amount or number of operations. The Bceao also specifies that the conditions applied to electronic money transactions between WAEMU countries are identical to those offered to transfers at the national level. These new provisions aim particularly to strengthen financial inclusion through better targeting of populations likely to benefit from free access; extend free transfers regionally; and improve the quality and availability of services and encourage the emergence of new uses. For Tossouve Renaude Martinie, professional in banking, Fintech and Mobile Money payments & electronic banking, the real transformation does not only lie in making certain transfers free. It lies in the ecosystem’s capacity to build more accessible, instantaneous, interoperable and available payments, while allowing the emergence of new uses. For banks, payment institutions, electronic money institutions, fintechs and other payment players, she considers that this also involves rethinking customer journeys, systems integration, platform availability, risk and fraud management, user experience and economic models linked to digital payments. “Pi-Spi is therefore not just a means of transferring money. It is an infrastructure that can contribute to sustainably transforming the payments ecosystem in UEMOA. And for professionals who wish to evolve in the fields of digital payment, interoperability and payment systems, understanding these transformations becomes essential,” explains Tossouve Renaude Martinie.
Demba DIENG
